Hiring, Payroll & Employment
in Hong Kong

Hire Employees and Contractors in Hong Kong

Project Global helps international businesses hire, onboard and manage employees and contractors in Hong Kong without needing to establish their own local entity. Through our established presence in Hong Kong and in-country expertise, we provide Employer of Record (EOR), contractor management, payroll, compliance, recruitment and workforce administration services.

Services available in Hong Kong:
香港国旗

关于香港

香港在 1997 年回归前一直是英国领土,现在是中国的一个特别行政区。如今,香港因其毗邻中国大陆和东亚的战略位置而成为著名的全球金融中心。该地区经济的特点是强调自由贸易、低税率和最少的政府干预。作为全球第八大贸易经济体,香港吸引了大量外国投资,并得益于来自邻国的多样化和丰富的劳动力,使其成为一个具有吸引力的商业企业和投资机会的地点。

香港:国家资源

货币

港元

首都:

香港,添马舰

语言

粤语 | 英语

方便经商

非常简单

人口规模

7.5M

增值税

不适用
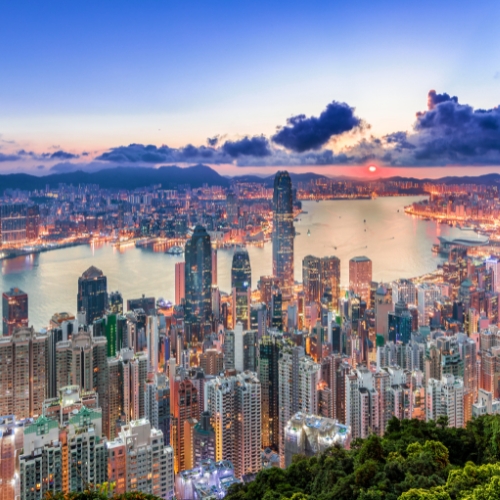
香港

Go Global in Hong Kong

我们的跨国客户信任我们,让我们为在香港工作的员工、承包商和自由职业者处理国际支付和合规事宜。

您可以使用我们的 "记录雇主"(EoR)服务,通过我们的法律实体聘用您的团队--让您的顶尖人才快速、轻松地入职。 

体验我们为您的企业和团队提供的世界级服务。

Explore Other APAC Employment Guides

Explore our country-specific guides covering employment, payroll, compliance and workforce management across APAC.
Australia

Australia

Source, onboard and manage workers in Australia
香港

印度

Source, onboard and manage workers in India
新加坡

新加坡

Source, onboard and manage workers in Singapore
泰国

泰国

Source, onboard and manage workers in Thailand
菲律宾

菲律宾

Source, onboard and manage workers in the Philippines
Global flags

View all Country Guides

Explore employment, payroll and compliance requirements by country

常见问题

香港全年有多个公众假期。国定假日包括

  • 农历新年(1 月/2 月)--庆祝活动持续数天,标志着农历的开始。
  • 清明节(四月)--祭祀祖先和扫墓的日子。
  • 劳动节(5 月 1 日)--庆祝工人的贡献。
  • 佛诞节(四月/五月)--纪念佛陀诞辰。
  • 香港特别行政区成立纪念日(7 月 1 日)--纪念香港回归中国周年。
  • 中秋节(九月/十月)--庆祝丰收和月圆的节日。
  • 国庆节(10 月 1 日)--庆祝中华人民共和国成立。
  • 重阳节(十月)--祭拜祖先和爬山的日子。
  • 圣诞节(12 月 25 日)--庆祝圣诞节。
  • 节礼日(12 月 26 日)--圣诞节后的公共假日。

除此之外,还有特定文化或传统纪念活动的法定假日。


香港的薪酬和补偿金主要受《雇佣条例》(第 57 章)规范。主要条款包括

  • 最低工资:香港制定了《最低工资条例》,规定雇主必须至少向雇员支付规定的每小时最低工资。该标准会定期更新。
  • 支付工资:雇主必须定期支付工资,至少每月一次,并且必须提供详细的工资报表,列明挣得的金额、扣除的费用和支付日期。
  • 休息日和加班:如果合同规定或公司政策要求,员工有权享有休息日,加班必须获得补偿。
  • 年假和公共假期:员工有权根据服务年限享受年假,并享有《雇佣条例》规定的带薪公共假期。
  • 离职金和长期服务金:根据法律规定,无故被解雇或完成长期任期的员工有资格领取离职金或长期服务金。

雇主必须遵守这些规定,以确保为员工提供公平、合法的补偿。

香港雇员有权享受多种假期,包括

  • 年假:员工有权享受带薪年假,年假随着服务年限的增长而增加。法定最低年假为 7 天,但根据雇佣合同,年假可能会更多。

  • Sick Leave: Employees accumulate paid sickness days at 2 days per month during the first 12 months of employment and 4 days per month thereafter, up to a maximum accumulation of 120 days. Eligible employees are entitled to sickness allowance at 80% of their average daily wages, subject to statutory requirements and medical certification. 

  • 事假:没有关于事假的法律规定;不过,一些雇主可能会根据公司政策提供事假。

  • Maternity Leave: Eligible employees are entitled to 14 weeks of paid maternity leave, payable at 80% of their average daily wages.

  • Paternity Leave: Eligible employees are entitled to 5 days of paid paternity leave, payable at 80% of their average daily wages.

  • Public Holidays: Employees are entitled to 15 statutory public holidays each year, with pay if they meet the eligibility criteria.

  • 其他假期:包括恩恤假(如丧假)、无薪假或公司具体政策规定的假期。


在香港,解雇员工有多种原因,包括裁员、业绩不佳、行为不当和健康欠佳。除非因严重不当行为而终止雇佣,否则一般都需要提前通知或支付代替通知的工资。在严重不当行为的情况下,解雇必须遵循公平的纪律处分程序,包括给予员工对指控做出回应的机会。休法定产假或参与劳资纠纷的员工在休假期间或纠纷过程中受到保护,不会被解雇。此外,解雇员工必须遵守《雇佣条例》的规定和任何适用的雇佣合同条款。

香港雇员的强制保险条款包括

雇员赔偿保险:雇主必须为因工受伤或患病的雇员提供该保险。它为医疗费用、收入损失和其他相关费用提供补偿。

强制性公积金(MPF):一种强制要求雇主和雇员共同供款的退休储蓄计划。雇主必须为其雇员缴纳强积金供款,帮助他们为退休储蓄。

这些保险计划对于保护员工福利、确保他们在工伤或退休时的经济保障至关重要。

An Employer of Record, or EOR, can employ a worker in Hong Kong for an overseas organisation that does not have its own local employment infrastructure. The EOR acts as the legal employer, while the client manages the person’s day-to-day responsibilities.
 
Project Global has a registered Hong Kong entity. However, each requirement must be assessed before Project Global confirms that an EOR arrangement is available, particularly where employment-agency or labour-supply licensing rules may apply. 
 

An EOR may be suitable when you want to employ someone in Hong Kong without creating and managing your own local employment operation. Establishing an entity may deserve consideration where the organisation is making a substantial or long-term commercial commitment to Hong Kong.
 
The decision should consider anticipated headcount, business activities, duration, visa requirements, operating costs and the level of local administration your organisation wants to manage. The existence of an entity alone may not resolve every employment or licensing requirement, so the proposed operating model should be reviewed before a decision is made.
 

The total cost of employing someone in Hong Kong includes more than salary. Depending on the employee and arrangement, it may include Mandatory Provident Fund contributions, employees’ compensation insurance, paid statutory entitlements, benefits and employment administration.
 
The cost will also depend on the employee’s age, immigration status, salary, working pattern and eligibility for particular statutory schemes. Current contribution limits, wage thresholds and statutory requirements should be applied when the estimate is prepared.
 

An EOR may be able to employ a foreign national in Hong Kong, but the proposed worker must have appropriate permission to live and work there. Holding a Hong Kong identity document or having permission to reside in Hong Kong does not necessarily mean that every type of work is permitted.

Evidence should be provided of the individual’s right to enter or remain in Hong Kong for the relevant contractual period. The proposed role, immigration status and employment structure should be checked before a start date is agreed.

Before the person starts, the employer should confirm their right to work, agree the employment terms and identify the information needed for payroll, insurance and statutory administration.
 
The checks required will depend on whether the individual will be an employee or an independent contractor. For employees, the employer should also establish whether Mandatory Provident Fund enrolment and employees’ compensation insurance apply. For contractors, the organisation should check the person’s business-registration evidence, tax position and actual working arrangements.
 

You can engage a genuinely independent contractor in Hong Kong, but the arrangement must operate as an independent business relationship in practice. Describing the person as a contractor in an agreement does not settle their status.
 
Hong Kong’s classification assessment considers factors including control over working methods and time, ownership of equipment, integration into the organisation, the ability to hire helpers, financial risk and responsibility for tax and insurance. The traditional practices of the person’s trade or profession may also be relevant.
 
No single factor should be considered in isolation. The complete working relationship should be reviewed before the engagement begins.
 

A person treated as self-employed may still be considered an employee if the real working relationship points towards employment. This can create exposure relating to statutory employment protections, leave, termination, insurance and other employer obligations.
 
Risk may be greater where the organisation controls how and when the work is performed, supplies the equipment, integrates the person into its operations and leaves the individual with little genuine opportunity to make a profit or suffer a loss. Responsibility for tax and insurance, the ability to engage helpers and the established practice of the profession may also affect the assessment.
 
A written contractor agreement is important, but it should accurately reflect how the arrangement operates.
 

Assess the proposed relationship before work begins and review it again if the role or working practices change. The assessment should examine control, working time, equipment, integration, delegation, financial risk and whether the individual is genuinely operating a business on their own account.
 
The contract should match the practical arrangement. For example, an agreement that describes the individual as independent will carry less weight if the client controls their schedule, methods, tools and daily activities.
 
The worker’s business registration, tax evidence and right-to-work position should also be checked. These checks do not prove that the individual is self-employed, but they help identify whether the proposed structure is credible and properly documented.
 

A person carrying on a trade, profession or business as a self-employed individual in Hong Kong will generally need to complete business registration with the Inland Revenue Department. Registration should usually be completed within one month of beginning the activity.

The relevant evidence may be a Business Registration Certificate or, where applicable, a Business Exemption Certificate. Registration evidence supports the onboarding process, but it does not by itself determine whether the person is genuinely self-employed. Their actual working relationship must still be assessed.
 

Hong Kong employers are required to maintain employees’ compensation insurance for employees falling within the applicable legislation. This requirement can apply regardless of whether employment is full-time, part-time, permanent or temporary.

Insurance should be arranged before employment begins and should reflect the organisation’s workforce and activities. A contractor’s position should be assessed separately because calling someone self-employed will not remove employer obligations if the relationship is employment in practice.
 

Part-time, casual and short-hours workers may still be employees. Eligibility for certain statutory benefits can depend on whether the person is employed under a “continuous contract” under Hong Kong employment legislation.
 
The precise continuous-contract test and its consequences should be checked against the rules in force when the person is engaged. Employers should not assume that a worker has no statutory entitlements simply because they work irregularly, for limited hours or on a casual basis.
 
The safest approach is to review the expected work pattern, contractual arrangement and statutory eligibility before deciding how leave, benefits and termination provisions will be managed.
 

The Mandatory Provident Fund, or MPF, is Hong Kong’s employment-based retirement savings system. Employer and employee obligations depend on factors including the person’s age, employment status, permitted exemptions and applicable income levels.
 
An employer should establish whether the employee must be enrolled, when enrolment is required and what contributions apply. Foreign nationals should not automatically be treated as exempt because exemption can depend on their circumstances and participation in an overseas retirement scheme.
 
MPF contribution limits and exemptions can change, so they should be checked for the particular employee when the employment cost is calculated.
 

Before terminating employment in Hong Kong, the employer should review the contract, applicable notice period, payment in lieu provisions, outstanding wages, accrued entitlements and whether any protected circumstances apply.
 
The employer should also consider whether severance or long-service payment may be relevant. The outcome can depend on the reason for termination, the employee’s length and continuity of service and the circumstances in which employment ends.
 
Termination should not be approached as a payroll step alone. The factual basis, documentation and statutory position should be reviewed before action is taken.
 

The process should combine talent sourcing with an early assessment of how the successful candidate can properly be engaged. Depending on the role and working arrangement, the person may require employment or may be suitable for a genuine independent-contractor structure.
 
This is particularly important for project-based media and technology roles. Industry practice or a short assignment does not override the practical classification factors, including control, integration, equipment, delegation and financial risk.
 
Job-placement activity is regulated in Hong Kong. An organisation providing job-placement services must hold an Employment Agency Licence or an applicable Certificate of Exemption before conducting regulated activity. The licensed delivery route should therefore be confirmed before accepting a recruitment requirement.
 

Project Global has a registered Hong Kong company and can help businesses explore options for engaging talent in Hong Kong.

The appropriate employment arrangement will depend on the proposed role, working practices and applicable local requirements. Project Global can assess your workforce needs and advise on the available engagement options to help ensure the proposed arrangement meets Hong Kong employment and compliance requirements.

Ask Project Global to assess your Hong Kong workforce requirement.
全球项目
隐私概述

本网站使用 Cookie,以便为您提供最佳的用户体验。Cookie 信息存储在您的浏览器中,其功能包括在您再次访问我们的网站时识别您的身份,以及帮助我们的团队了解您对网站的哪些部分最感兴趣和最有用。