Hiring, Payroll & Employment
in Ireland

Hire Employees and Contractors in Ireland

Project Global helps international businesses hire, onboard and manage employees and contractors in Ireland without needing to establish their own local entity. Through our established presence in Ireland and in-country expertise, we provide Employer of Record (EOR), contractor management, payroll, compliance, recruitment and workforce administration services.

Services available in Ireland:

Irland Flagge

Über Irland

Ireland, known as the "Emerald Isle," is renowned for its cultural heritage and vibrant arts. It has a strong economy in technology, pharmaceuticals, and financial services. Celebrated for its innovation and education, Ireland is a key player in global trade and economic growth, influencing international markets and driving job creation.

Irland: Länderressourcen

Währung:

Euro (EUR)

Kapital:

Dublin

Sprache:

Irisch & Englisch

Leichtigkeit der Geschäftstätigkeit

Einfach

Bevölkerung

5.5M

MEHRWERTSTEUER

23%

Irland

Globales Engagement in Irland

Unsere multinationalen Kunden vertrauen darauf, dass wir uns um ihre Zahlungen und die Einhaltung der Vorschriften für Angestellte und Auftragnehmer/Freelancer in Irland kümmern.

Sie können unseren Employer of Record (EoR) Service nutzen, um Ihr Team über unsere juristische Person einzustellen - so können Sie Ihre Top-Talente schnell und einfach an Bord holen. 

Explore Other European Employment Guides

Explore our country-specific guides covering employment, payroll, compliance and workforce management across Europe.
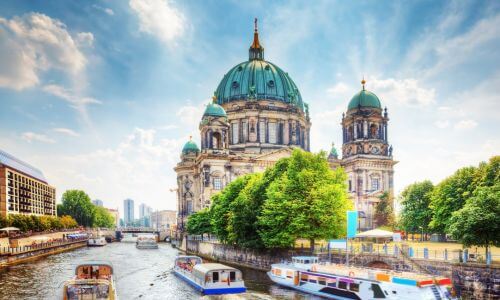
Germany, Berlin

Deutschland

Source, onboard and manage workers in Germany
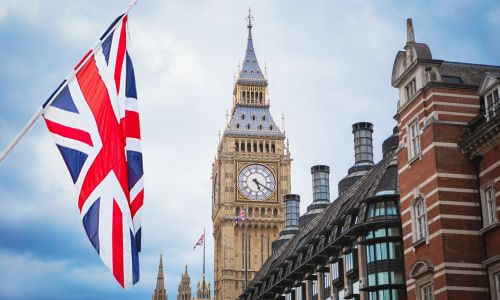
Vereinigtes Königreich

Vereinigtes Königreich

Source, onboard and manage workers in the UK
Global flags

View all Country Guides

Explore employment, payroll and compliance requirements by country

FAQ's

In Irland gibt es neun gesetzliche Feiertage: Neujahr, St. Patrick's Day, Ostermontag, der erste Montag im Mai, Juni und August, der letzte Montag im Oktober, der erste Weihnachtstag und der St. Stephen's Day

Die Arbeitnehmer in Irland haben Anspruch auf mindestens den nationalen Mindestlohn, der jährlich überprüft wird. Die Arbeitgeber sind verpflichtet, Gehaltsabrechnungen vorzulegen, auf denen Bruttolohn, Abzüge und Nettolohn aufgeführt sind. Überstundenvergütungen und andere Zulagen müssen ebenfalls klar im Arbeitsvertrag festgehalten werden

Arbeitnehmer in Irland haben Anspruch auf verschiedene Arten von Urlaub, unter anderem:

  • Jahresurlaub: Mindestens vier Wochen bezahlter Urlaub pro Jahr.
  • Mutterschaftsurlaub: 26 Wochen bezahlter Urlaub mit der Möglichkeit, weitere 16 Wochen unbezahlten Urlaub zu nehmen.
  • Parental leave: 26 weeks of unpaid leave for each parent per child.
  • Sick leave: Eligible employees are entitled to statutory sick leave under Ireland’s Statutory Sick Leave Scheme. Statutory sick leave is paid by the employer at 70% of normal wages, subject to applicable caps and qualifying criteria.

Der Arbeitgeber kann das Arbeitsverhältnis aus Gründen der Befähigung, des Verhaltens, der Entlassung oder aus anderen wichtigen Gründen kündigen. Die Beendigung des Arbeitsverhältnisses muss nach einem fairen Verfahren erfolgen, d. h. es muss eine Kündigungsfrist eingehalten werden und der Arbeitnehmer muss Gelegenheit zur Stellungnahme erhalten. Klagen wegen ungerechtfertigter Entlassung können bei der Workplace Relations Commission (WRC) eingereicht werden

Die Arbeitgeber sind verpflichtet, dafür zu sorgen, dass die Arbeitnehmer durch das Sozialversicherungssystem abgedeckt sind, das eine Krankenversicherung, eine Versicherung gegen Arbeitsunfälle und eine lohnbezogene Sozialversicherung (PRSI) umfasst. Diese Beiträge werden in der Regel zwischen dem Arbeitgeber und dem Arbeitnehmer geteilt

You can hire employees in Ireland without establishing a local legal entity by using an Employer of Record (EOR) service. An EOR acts as the legal employer, handling employment contracts, payroll and local employment compliance, while you manage the employee’s day-to-day work.

Project Global helps businesses hire talent in Ireland through its local Irish entity, Icon Peak Ltd. We can support compliant employment arrangements, including employed agency-worker contracts where engaging someone as a self-employed contractor may not be appropriate. This allows businesses to access Irish talent without the time, cost and complexity of setting up their own company.

Need to employ someone in Ireland? Discuss your EOR requirement with us.

An EOR can be a practical option when you need to employ people in Ireland without creating and operating your own local employment infrastructure. Establishing an Irish entity may be more appropriate for some substantial or long-term operations, but there is no single headcount at which it automatically becomes the better choice.
 
The decision should consider your expected headcount, business activities, investment plans, employment-permit requirements, timescale and the local administration your organisation is prepared to manage. An individual assessment is more reliable than making the decision solely on cost per employee.
 
The total cost of employment in Ireland includes more than salary. Depending on the employee and arrangement, costs may include employer Pay-Related Social Insurance, pension contributions, paid leave, statutory sick leave, public-holiday entitlements and the cost of employment administration.
 
Project Global can calculate the likely cost using the person’s salary, working pattern, pension position, proposed benefits and employment terms. PRSI rates, pension obligations and statutory benefits should be calculated using the requirements in force when the employee starts.
 

An EOR may be able to employ a non-EEA national in Ireland, but the worker must have the appropriate immigration status and permission to work. A non-EEA national will commonly need a valid employment permit unless an exemption applies.
 
The correct route depends on the person’s nationality, immigration status, occupation, salary and proposed employment. Employment should not begin until the necessary right-to-work evidence and any required permission have been confirmed.
 

Before an employee starts, the employer should confirm their right to work, agree the employment terms and collect the information required for payroll and employment administration.
 
The employer registers the new employment with Revenue. Revenue then issues a Revenue Payroll Notification, or RPN, which provides the tax credits and cut-off information to apply through payroll. The details needed to establish the employment arrangement include the role, location, hours, salary, start date, employment term, notice period, benefits and any required checks.
 

You can engage a genuinely self-employed contractor in Ireland, but the structure must reflect how the person will work in practice. Calling someone a contractor in an agreement does not determine their employment or tax status.
 
Ireland’s Revenue guidance uses a five-question framework. It considers whether there is an exchange of work for pay, whether personal service is required, whether the organisation has sufficient control, whether the overall circumstances point towards employment or independent business, and whether the relevant legislation changes the assessment.
 
Where the proposed arrangement points towards employment, Project Global’s Irish entity can offer an employed agency-worker route rather than relying on a potentially unsuitable contractor structure.

A worker who is described and paid as self-employed may still be considered an employee for tax, social-insurance or employment-rights purposes. This can create obligations relating to PAYE, Universal Social Charge, PRSI and statutory employment protections.
 
Irish Revenue states that businesses making payments to individuals must determine the correct status from the facts and circumstances of each relationship. The written contract matters, but it may not be the only determining factor. The practical working arrangement must also be considered.
 
Tax, PRSI and employment rights are considered under separate legislative frameworks by different Irish bodies. A status decision made for one purpose does not necessarily bind the bodies responsible for the others. This is why a classification review should consider more than tax treatment alone.

Yes. A short assignment, one-off job, gig or shift can potentially be treated as employment for Irish tax purposes. The absence of a continuing obligation to provide future work does not automatically establish that the person is self-employed.
 
Revenue’s guidance says that even a single engagement can give rise to a contract of employment where work is performed in return for payment, subject to the rest of the classification framework. Businesses should therefore assess the nature of the work, personal-service requirement, control and complete working arrangement rather than relying on the assignment’s duration.
 
This is particularly relevant to media, production, events and project-based roles, where short engagements are common but may still operate like employment.
 

Start by assessing the proposed working relationship before the contractor begins. The assessment should examine the work-for-pay arrangement, whether the individual must perform the work personally, the organisation’s right of control and whether the person is genuinely operating an independent business.
 
The organisation should then ensure that the written terms match the actual arrangement. Revenue’s guidance makes clear that the contract may be considered alongside the facts and circumstances of the relationship. A contractor agreement will not resolve the risk if the working practices point towards employment.
 
Where classification risk remains, employment through an appropriate EOR or agency-worker arrangement may offer a more suitable structure. Project Global can offer employed agency-worker contracts for roles in Ireland where classification risk is identified.
 
A genuine ability to provide a substitute can support self-employed status, but substitution is not a standalone answer. The nature and practical usability of the right matter.
 
Revenue guidance distinguishes between an unrestricted ability to delegate the work and a limited clause under which the organisation retains control over the substitute. Restrictions on who can act as a substitute, whether prior approval is required, who selects and pays the replacement, and whether the organisation can refuse them may indicate that personal service is still required.
 
A substitution clause that exists only on paper should not be relied upon without reviewing the actual working practices and the rest of the classification framework.
 

Where a worker is employed by an agency and assigned temporarily to work under a client’s supervision and direction, Irish agency-worker protections may apply.

In Ireland, applicable agency workers are entitled from the first day of the assignment to the same basic working and employment conditions as if they had been recruited directly into the same or a similar role. This includes basic pay, working hours, applicable overtime rates, rest breaks, night work, annual leave and public holidays.

Agency workers should also receive access to relevant workplace facilities and information about permanent vacancies, subject to the applicable rules. The client must give the employment agency accurate information about comparable pay and conditions so that the agency can meet its obligations.

This means an Irish EOR arrangement requires cooperation between the EOR and the client. It is not simply a payroll transaction.

A freelancer may operate in Ireland as a sole trader, contractor or through an appropriate business structure. Sole traders must register as self-employed with Revenue, while a person using a separate business name may also need to register that name with the Companies Registration Office.

Individuals are identified for tax purposes using a Personal Public Service Number, or PPS number. Businesses and other non-natural persons may use a Tax Reference Number. Once registered, a sole trader generally uses Revenue’s online services to file returns and make tax payments.

Before engagement, the organisation should also review the proposed worker’s classification, tax-registration evidence and right to work. Project Global can support freelancer engagement and self-billing. 

Employment costs in Ireland can include salary, employer PRSI, pension contributions where applicable, paid annual leave, public-holiday entitlements and statutory sick leave. The exact cost depends on the employee’s salary, working pattern, pension status and employment terms.
 
Most employees are entitled to a minimum of four weeks’ paid annual leave. Full-time employees are also entitled to Ireland’s public holidays, while qualifying part-time employees have related entitlements. Overtime is generally a contractual matter, so the employment contract should explain whether overtime is required and how it will be treated.
 
Ireland also has family-related leave, statutory sick leave and pension auto-enrolment requirements for eligible employees. Contribution rates, thresholds and individual entitlements can change and should be checked when the employment cost is calculated.

Project Global can help organisations define the requirement, source specialist talent and then consider how the successful candidate should be engaged. Depending on the role and working arrangement, the person may be employed through an EOR or engaged as a genuinely independent contractor.
 
This is particularly important for project-based media and technology roles. Irish Revenue’s worker-status guidance applies across sectors, expressly discusses media work and makes clear that a single job, gig or shift can potentially be employment for tax purposes.
 
Combining recruitment with an early assessment of the employment model helps avoid finding the right person and only later discovering that the planned contractor structure is unsuitable.
 

Yes. Project Global has an Irish entity, Icon Peak Ltd. Project Global can also offer employed agency-worker contracts where a proposed engagement presents worker-classification risk.

The employment arrangement can include payroll, PAYE, PRSI, employment documentation and ongoing administration. Its precise structure will depend on the role, working practices, right-to-work position and information supplied by the client.
Speak to Project Global about employing someone in Ireland.

Projekt Global
Überblick über den Datenschutz

Diese Website verwendet Cookies, damit wir Ihnen die bestmögliche Benutzererfahrung bieten können. Cookie-Informationen werden in Ihrem Browser gespeichert und dienen dazu, Sie wiederzuerkennen, wenn Sie auf unsere Website zurückkehren, und unserem Team zu helfen, zu verstehen, welche Bereiche der Website Sie am interessantesten und nützlichsten finden.